Summary:
You’ve got an accepted offer, a closing date circled on the calendar, and about a dozen things demanding your attention at once. The survey probably feels like a box to check — something your attorney mentioned, something the lender may or may not require, something you’ll get to when you get to it.
That’s usually when things go sideways. In Nassau County’s fall real estate market, when transactions are moving quickly and surveyors are booked out, “getting to it” a week before closing isn’t a plan — it’s a gamble. Here’s what you actually need to know to keep your deal on track.
Survey for Home Purchase: What Nassau County Buyers Need to Know
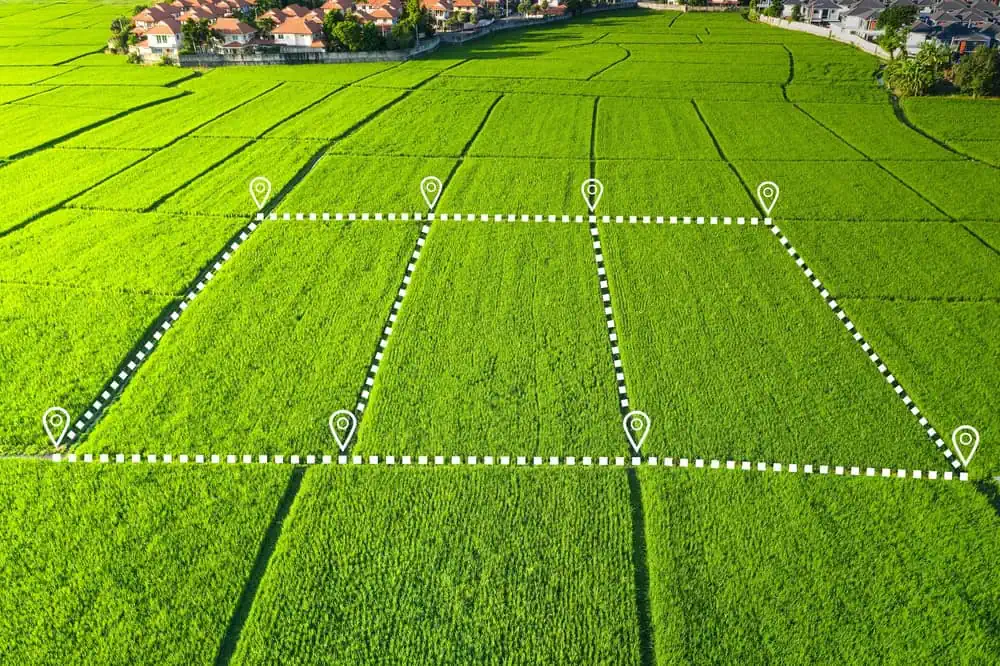
Not all surveys are the same, and the type you need depends on your specific transaction. For most residential closings in Nassau County, what’s required is a location survey — also called a title survey. This confirms that the house, garage, fences, shed, pool, and any other structures on the property sit within the legal boundaries described in the deed. The completed map gets certified to your lender, your title company, your attorney, and you.
A boundary survey goes further, physically staking out property corners and establishing exact lines. If you’re planning to build a fence, add an addition, or just want a clear record of where your property ends and your neighbor’s begins, a boundary survey gives you that documentation. Understanding which one your transaction calls for — before you call us — saves time and avoids back-and-forth at the worst possible moment.
Closing Survey Requirements: What Lenders and Title Companies Actually Expect

Here’s where a lot of buyers get tripped up. Some lenders have quietly dropped the survey requirement for residential transactions — which leads buyers to assume they don’t need one at all. That assumption can be costly.
Even when your lender doesn’t require a survey, your title company very likely does — or at minimum, will issue your title insurance policy with a “survey exception” if you don’t provide one. That exception removes coverage for anything a current survey would have revealed: boundary discrepancies, encroachments, easements, improvements that cross a property line. You’re paying for title insurance to protect yourself, and the survey exception quietly carves out some of the most common real-world risks.
Your real estate attorney will almost always recommend getting a survey regardless of what the lender says. In New York, attorneys are involved in every residential closing, and the good ones know that a Nassau County home without a current survey is a liability waiting to surface — whether at this closing or the next one.
It’s also worth understanding what “current” means in this context. A survey from a previous owner, or one that’s more than five to ten years old, may not satisfy your lender or title company. And even if it technically does, it likely doesn’t reflect decades of additions, pools, fences, and other changes made since it was done. Much of Nassau County’s housing stock is predominantly post-World War II — built during the Levittown era of the late 1940s and 1950s. Original surveys from that period are often 60 or 70 years old. They don’t show the sunroom that was added in 1987, the vinyl fence that went up in 2003, or the above-ground pool that’s been there since 2010. A new survey does.
Under New York State law, only a licensed and registered NYS Land Surveyor can produce a legal survey. That means engineers, architects, real estate agents, and contractors cannot legally make boundary determinations — regardless of what they tell you. When you’re hiring a surveyor, verify that they hold a current NYS license issued through the State Education Department.
Survey Timeline for Closing: When to Order and What Can Go Wrong
The single most common survey mistake buyers make is ordering too late. The right time to schedule your survey is immediately after your purchase contract is signed — not two weeks before closing, not when your attorney reminds you, and definitely not when you realize you haven’t done it yet.
Here’s why timing matters so much. Mortgage rate locks typically run 30 to 60 days. If a survey delay pushes your closing past the lock expiration, you may be looking at a rate renegotiation — which, depending on where rates are sitting, could mean a meaningfully higher monthly payment. Add in the cost of rescheduling movers, extending temporary housing, or dealing with a lease that’s already ended, and a survey delay stops being a minor inconvenience and becomes a real financial problem.
During the fall real estate season in Nassau County — roughly September through November — transaction volume is high and surveyor schedules fill up fast. Families want to be settled before the holidays. Buyers who spent the summer searching are finally closing. Year-end financial deadlines push some transactions to move faster than expected. All of that creates demand that outpaces capacity, and the surveyors who are worth hiring tend to book out weeks in advance during this period.
The practical implication is straightforward: if you’re in contract on a Nassau County home right now and you haven’t scheduled your survey, that’s the first call to make. Not tomorrow. Today. We maintain an 8-day average turnaround, which gives you meaningful breathing room in a 45-day closing window — but only if you start the clock early enough for that turnaround to matter.
Weather is another factor worth keeping in mind. Fall fieldwork in Nassau County is generally manageable, but if a transaction stalls and pushes into December or January, winter conditions can delay on-site survey work and compress schedules further. Getting ahead of the calendar in September or October is always the better move.
What Makes a Nassau County Closing Survey More Complicated Than You'd Expect
Nassau County isn’t a straightforward market to survey. Lots are small — many under a quarter acre — with tight setbacks and properties that share boundary lines with multiple neighbors. The density of the housing stock means encroachments are more common than most buyers expect: a fence that’s six inches over the line, a driveway that clips a property corner, a shed that technically sits on the adjacent lot. These aren’t rare edge cases. They’re routine findings in a county where houses were built close together decades ago and have changed hands multiple times since.
Add to that the flood zone complexity along Nassau County’s South Shore. Communities like Long Beach, Oceanside, Freeport, Merrick, and Massapequa carry significant flood risk, especially in the years since Hurricane Sandy reshaped what lenders and insurers require. For properties in or near a flood zone, a Flood Elevation Certificate is often needed alongside the closing survey — and getting both from us saves time and coordination headaches.
Encroachments and Easements: What Happens When the Survey Finds Something
One of the fears buyers carry into the survey process is the idea that a problem on the survey means the deal falls apart. That’s rarely how it plays out. Most survey findings — an encroachment, an easement, a boundary discrepancy — are manageable if you have time to deal with them. The issue isn’t finding a problem. The issue is finding one the week before closing with no room to maneuver.
An encroachment, for example, might be resolved through a title insurance endorsement, a written agreement with the neighboring property owner, or a minor boundary adjustment. None of those are fast processes, but they’re workable if you’ve built enough time into your closing timeline. If you ordered your survey in week one of the contract period and the encroachment surfaces in week two, you have weeks to work through it. If you ordered in week six of a seven-week closing window, you don’t.
Easements are another common finding in Nassau County transactions. Utility easements — for power lines, gas lines, drainage — run across many residential properties and are typically disclosed in the deed, but a current survey makes them visible on the map. Buyers should understand that easements don’t necessarily affect property value or usability in a meaningful way, but they do need to be disclosed and accounted for in the title insurance policy. Your attorney and title company will walk you through what each one means for your specific situation.
The broader point is that a survey finding isn’t a verdict — it’s information. And information is only useful if you have time to act on it. That’s the real argument for ordering early, working with a surveyor who communicates clearly, and not treating the survey as an afterthought in the closing process.
How the Right Surveyor Makes the Whole Process Easier in Nassau County
Not every surveyor is the same, and in a market like Nassau County, local knowledge genuinely matters. The deed records, prior surveys, municipal files, and boundary histories that a surveyor needs to research before setting foot on your property are specific to this county — to the Town of Hempstead, the Town of Oyster Bay, the Town of North Hempstead, and the dozens of incorporated villages within them. We’ve been working these records for over 50 years and have seen the quirks, the inconsistencies, and the outdated documentation that can slow down a survey if you don’t know where to look.
Turnaround time is the other variable that separates surveyors in a time-sensitive transaction. We maintain an 8-day average turnaround — a concrete commitment, not “a few weeks” or “as soon as we can get to it.” When your closing date is fixed and your rate lock is ticking, knowing exactly what to expect from your surveyor is part of what makes the rest of the closing process manageable.
Communication matters too, and it’s where the industry has a well-documented problem. Buyers regularly report leaving multiple voicemails with no response, not knowing when the surveyor will show up, and receiving a technical map with no explanation of what it shows. We believe the survey report shouldn’t raise more questions than it answers. We translate findings into plain language, tell you what was found, what it means for your transaction, and what — if anything — needs to happen next.
One practical advantage worth knowing: if you use us for your original purchase survey and later need an update for refinancing or resale, you’re not starting from scratch. We already have your property on file, which typically means a faster and more cost-effective inspection update rather than a full new survey. Over the life of a Nassau County home — where the median price exceeds $800,000 and owners often stay for decades — that kind of continuity adds up.
Getting Your Nassau County Real Estate Closing Survey Right the First Time
The survey is rarely the most exciting part of buying a home. But it’s one of the few steps in the process where moving too slowly has a direct cost — a delayed closing, an expired rate lock, a title insurance gap that doesn’t surface until you try to sell or refinance years down the road.
In Nassau County’s fall market, where transactions move fast and good surveyors book up, the best thing you can do is get ahead of it. Order immediately after contract signing, confirm your surveyor is licensed in New York State, and make sure they can deliver within your closing window.
If you have questions about what your specific transaction requires — or you’re ready to get scheduled — we’ve been serving Nassau County, Suffolk County, and Queens from Syosset, NY for over 50 years. Reach out and we’ll tell you exactly what you need and when we can have it done.